European Inverter Shipments Projected To Reach Ninety Gigawatts
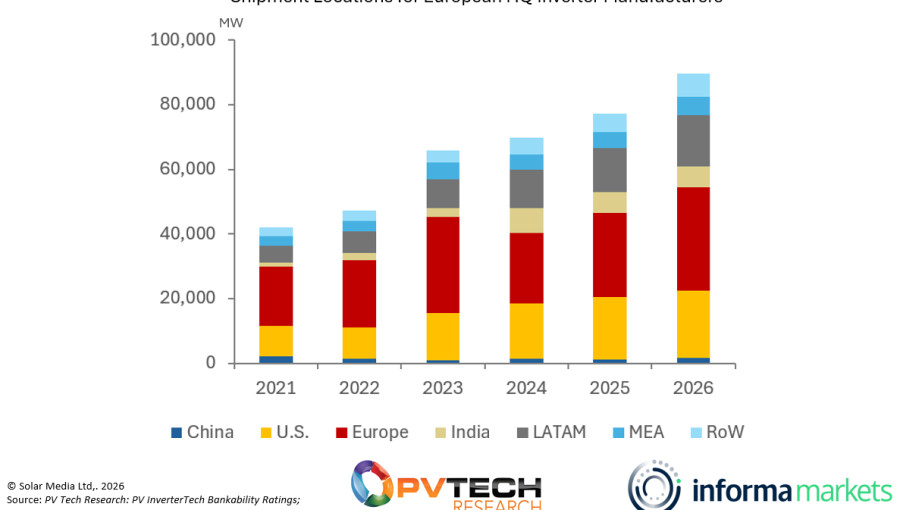
European-headquartered inverter manufacturers are projected to reach a significant milestone this year, with total shipments expected to hit nearly 90GW. This figure marks a substantial rise of 12GW compared to 2025 and doubles the output recorded in 2021. As the industry continues to expand, Europe remains the primary destination for these products, accounting for approximately one-third of total shipments. This growth highlights the region's strengthening position in the global solar supply chain, particularly as domestic manufacturing capacity for solar and energy storage inverters has successfully surpassed the 100GWac threshold earlier this year.
The European inverter sector has demonstrated more resilience and success in reshoring production compared to the solar module industry. Currently, Europe stands as the largest hub for inverter manufacturing outside of China. Data indicates that 90% of the continent's 100GW annual nameplate manufacturing capacity is held by companies headquartered within Europe. This industrial strength is largely driven by two major players, Germany’s SMA Solar and Spain’s Power Electronics, which dominate both the manufacturing output and the total volume of shipments.
While Europe remains the primary market, these manufacturers are also seeing significant demand in the United States and Latin America. Despite the implementation of a ban on foreign-produced inverters in the U.S. earlier this July, the region remains a key destination for European firms. Year-on-year growth trends show Europe leading with an increase of nearly 6GW in shipments, followed by Latin America with 2.2GW and the U.S. with 1.6GW. These findings, derived from internal market research, underscore the evolving landscape of the global inverter market and the pivotal role of European manufacturers in supporting international solar and storage deployment.